


The chip shortage of 2021 parked half-finished pickup trucks in fields, but the trucks eventually shipped once the missing semiconductors arrived. There is a smaller component that would be harder to wait out, because it has no domestic substitute at scale and almost no stockpile behind it.
It is the sintered neodymium magnet, the strongest permanent magnet ever commercialized. It turns electricity into motion in electric vehicle motors, power windows, windshield wipers, seat adjusters and speakers. The magnet also sits inside wind turbines, factory robots, drones and guided weapons. China produces roughly 90 percent of the world’s supply, and 2025 offered a live demonstration of what happens when the flow slows.
What it takes to make a sintered magnet
Making a sintered magnet is a metallurgical gauntlet. Neodymium and praseodymium must be separated from ore, reduced to metal, melted into a precise alloy, milled into a powder a few microns across, pressed into shape inside a magnetic field, and then sintered in a vacuum furnace at more than 1,000 degrees Celsius.

Magnets destined for hot environments, like an EV motor or a missile fin, also need traces of heavy rare earths such as dysprosium and terbium worked into the grain structure so they keep their magnetism under heat. Every step has narrow tolerances. And for most of the world’s output, every step happens in China.
How the know-how ended up there
The concentration was not an accident of geology. The United States invented much of the technology. General Motors’ magnet subsidiary Magnequench was sold in 1995 to a consortium with ties to Chinese state firms, and its Indiana production moved to China within a decade.
Beijing then spent thirty years treating mining, refining and magnet-making as a strategic industry, while low prices and environmental costs pushed Western producers out. By the time Washington rediscovered the issue, China held not just the mines but the process engineers, the furnace suppliers and the patents built around them.
The week the choke point showed
On April 4, 2025, China answered American tariffs by requiring export licenses for seven heavy rare earths and for permanent magnets. According to the Center for Strategic and International Studies, the announcement sent global supply chains into a tailspin within weeks.

Ford idled its Chicago Explorer plant for a week when a factory ran out of magnets. CEO Jim Farley described the supply as “day to day” and “hand-to-mouth”, with export applications approved one at a time. A Volvo plant in South Carolina paused too, Germany’s auto lobby warned of outright production halts, and the licenses eventually granted to suppliers of GM, Ford and Stellantis were reported to be temporary, valid for about six months.
The aftershock never fully faded. CSIS found that even after exports resumed, European imports rebounded while American imports never returned to their 2024 levels, still falling 11 percent year over year as late as November 2025.
The American magnet plants racing to catch up
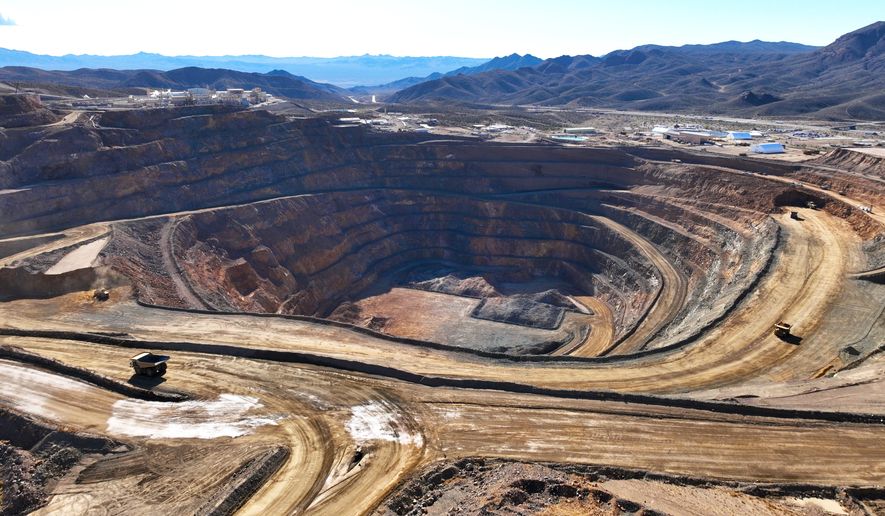
The response is the largest magnet buildout in U.S. history. MP Materials has begun commercial metal and automotive-grade magnet production at its Independence plant in Fort Worth, Texas, fed by its own Mountain Pass mine in California and backed by a Defense Department deal that included a $400 million investment and a ten-year price floor. The company is evaluating a roughly $1.2 billion magnet campus north of Fort Worth.
In Sumter, South Carolina, a plant tied to Germany’s VAC is ramping about 2,000 tons of capacity, expandable to 12,000. Vulcan Elements announced a $1.4 billion partnership with the U.S. government to build a 10,000-ton facility, USA Rare Earth is commissioning lines in Oklahoma, and Noveon Magnetics recycles old magnets into new ones in Texas.
The gap is still wide. Industry analyses put total non-Chinese capacity at roughly 8,000 to 10,000 metric tons a year, most of it still in customer qualification, against Commerce Department estimates of 3,000 to 4,000 tons for American defense demand alone. A Pentagon ban on Chinese magnets takes effect in January 2027.
What a magnet disruption would hit first
Automakers would feel it first, as they did in 2025, because a car contains dozens of small magnet motors and assembly lines carry only weeks of parts. The next wave would reach appliance makers, industrial automation and wind turbine installers, which use hundreds of pounds of magnet material per machine. Defense would be competing for the same qualified supply.
The chip shortage stopped car production for months and became a household story. The magnet lesson of 2025 was quieter but arguably starker: the choke point sits in a component most Americans have never seen, and the factories meant to replace it are still being built.
This article was constructed with the assistance of artificial intelligence and published by a member of The Washington Times' AI News Desk team. The contents of this report are based solely on The Washington Times' original reporting, wire services, and/or other sources cited within the report. For more information, please read our AI policy or contact Steve Fink, Director of Artificial Intelligence, at sfink@washingtontimes.com
The Washington Times AI Ethics Newsroom Committee can be reached at aispotlight@washingtontimes.com.
Please read our comment policy before commenting.