


OPINION:
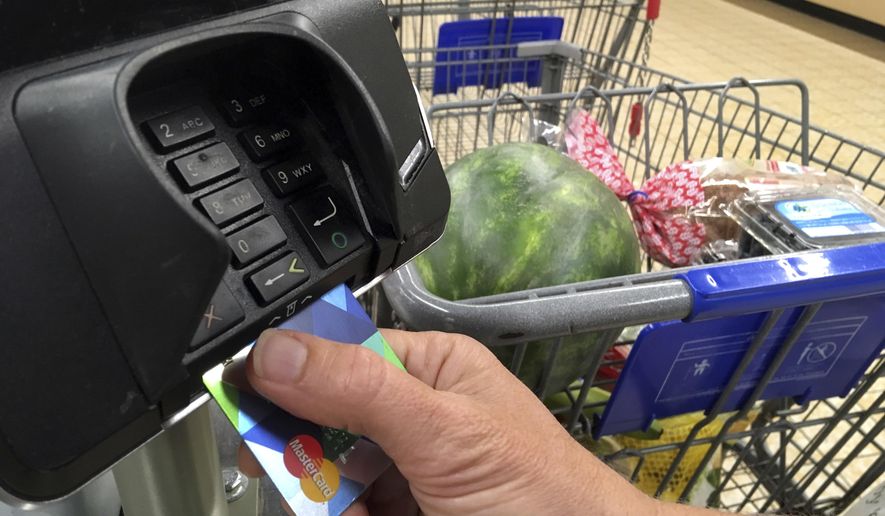
Few charges draw complaints from as many directions as the card swipe fee. Merchants resent the cut that card-issuing banks and payment networks take from every sale, and consumers resent checkout fees for paying by credit card.
Under that pressure, states have begun tiptoeing toward regulating interchange fees, or swipe fees, themselves. The first to act, Illinois, reads federal banking law in a way that lets an out-of-state bank escape its rules only by opening a physical branch there. The Federal Deposit Insurance Corp. has rightly proposed a rule to end that absurdity.
Illinois’ Interchange Fee Prohibition Act, set to take effect in July 2027, bars banks from collecting swipe fees on the sales tax and tip portion of a purchase. But federal law exempts national banks from this kind of state regulation, and Congress extended this protection to state-chartered banks to create parity.
People were interested in these podcasts
Illinois reads that protection as covering only those with a physical branch in the state. A small bank in Iowa serving Illinois customers from across the line may have to comply; an identical institution with an Illinois branch is exempt.
That’s wrong, and the FDIC is right to try to fix it.
States have a legitimate, long-standing role in protecting consumers and regulating commerce within their borders. But the Constitution gives Congress the power to regulate commerce among the states, and for good reason. Without a strong defense of Commerce Clause principles, a few states can bully the rest into following their rules. For multi-state banks, Congress has already set a reasonable standard.
Anyone who has worked on state policy, as I did in Arizona, knows the governing principle: in-state presence. An out-of-state business with a substantial in-state presence — such as a physical location — answers to that state’s rules.
When the Supreme Court’s 2018 Wayfair decision let states require remote sellers to collect sales tax, the fight was over whether less than a physical presence could count. Nobody ever suggested opening a store in Arizona would exempt a seller from its sales tax.
Illinois’ reading of federal banking law produces exactly that absurd result. The provision at issue, from the Riegle-Neal Act, refers to out-of-state banks’ “branches” in the host state, and Illinois reads that word as a limit. Approve a card purchase for a customer passing through Illinois, with no physical location there, and Illinois may say you are subject to its law. Open a branch, and suddenly you are exempt.
The result is a regulatory reach that shrinks as a bank’s presence grows. The few state banks based outside Illinois but with a branch there would be exempt, while the 3,185 state banks the FDIC identifies as potentially affected (most of them small) would not. Those banks could spend the resources to comply, but to get an exemption, they would perversely have to open a branch there.
That’s not what Congress set out to do. Riegle-Neal was a law about interstate banking and branching, written when banks served customers through branches and the first iPhone was more than a decade away. When Congress amended it in 1997, the bill’s sponsor was plain about the goal: “The essence of this legislation is to provide parity between state-chartered banks and national banks.”
Turning a word that described 1990s banking into a penalty on modern remote service banking gets that purpose backward and destroys parity.
The FDIC’s proposal applies the sensible reading. Where a host state’s law does not apply to an out-of-state national bank, it does not apply to an out-of-state state bank either, branch or no branch. The rule does not replace state regulation with federal regulation; it restores common sense and legislative intent to a 1990s-era statute.
If anything, Illinois’ reading works against state authority. The dual banking system, which lets a bank choose a state or federal charter, is itself an expression of federalism. Make the state charter the costlier one, and, as the FDIC observes, banks could shift to federal charters. That would be a strange victory indeed for states’ rights.
It also would be an expensive one. The FDIC estimates the affected state banks would spend about $308 million up front and nearly $7 million a year complying, all to transfer roughly $2.3 million a year in fees from banks to merchants. With 11 other states having explored similar legislation, the problem is unlikely to stay in Illinois.
If federal law has gone too far or failed to account for state needs in a card-dependent, network-based economy, it’s Congress’ job to amend it. But no reasonable reading of that framework would exempt a bank for moving into a state while penalizing its competitor for staying home.
The FDIC has proposed saying that clearly. It should finalize the rule. A bank shouldn’t have to move into Illinois to get out from under Illinois law.
• Glenn Farley is a research fellow in Tax Policy at The Heritage Foundation, where he focuses on improving federal tax and fiscal efficiency. Previously he was chief economist and tax policy adviser to Arizona Gov. Doug Ducey.
Please read our comment policy before commenting.